All Categories
Featured

Optimizing Indexed Universal Life Growth Potential in Retirement
Table of Contents
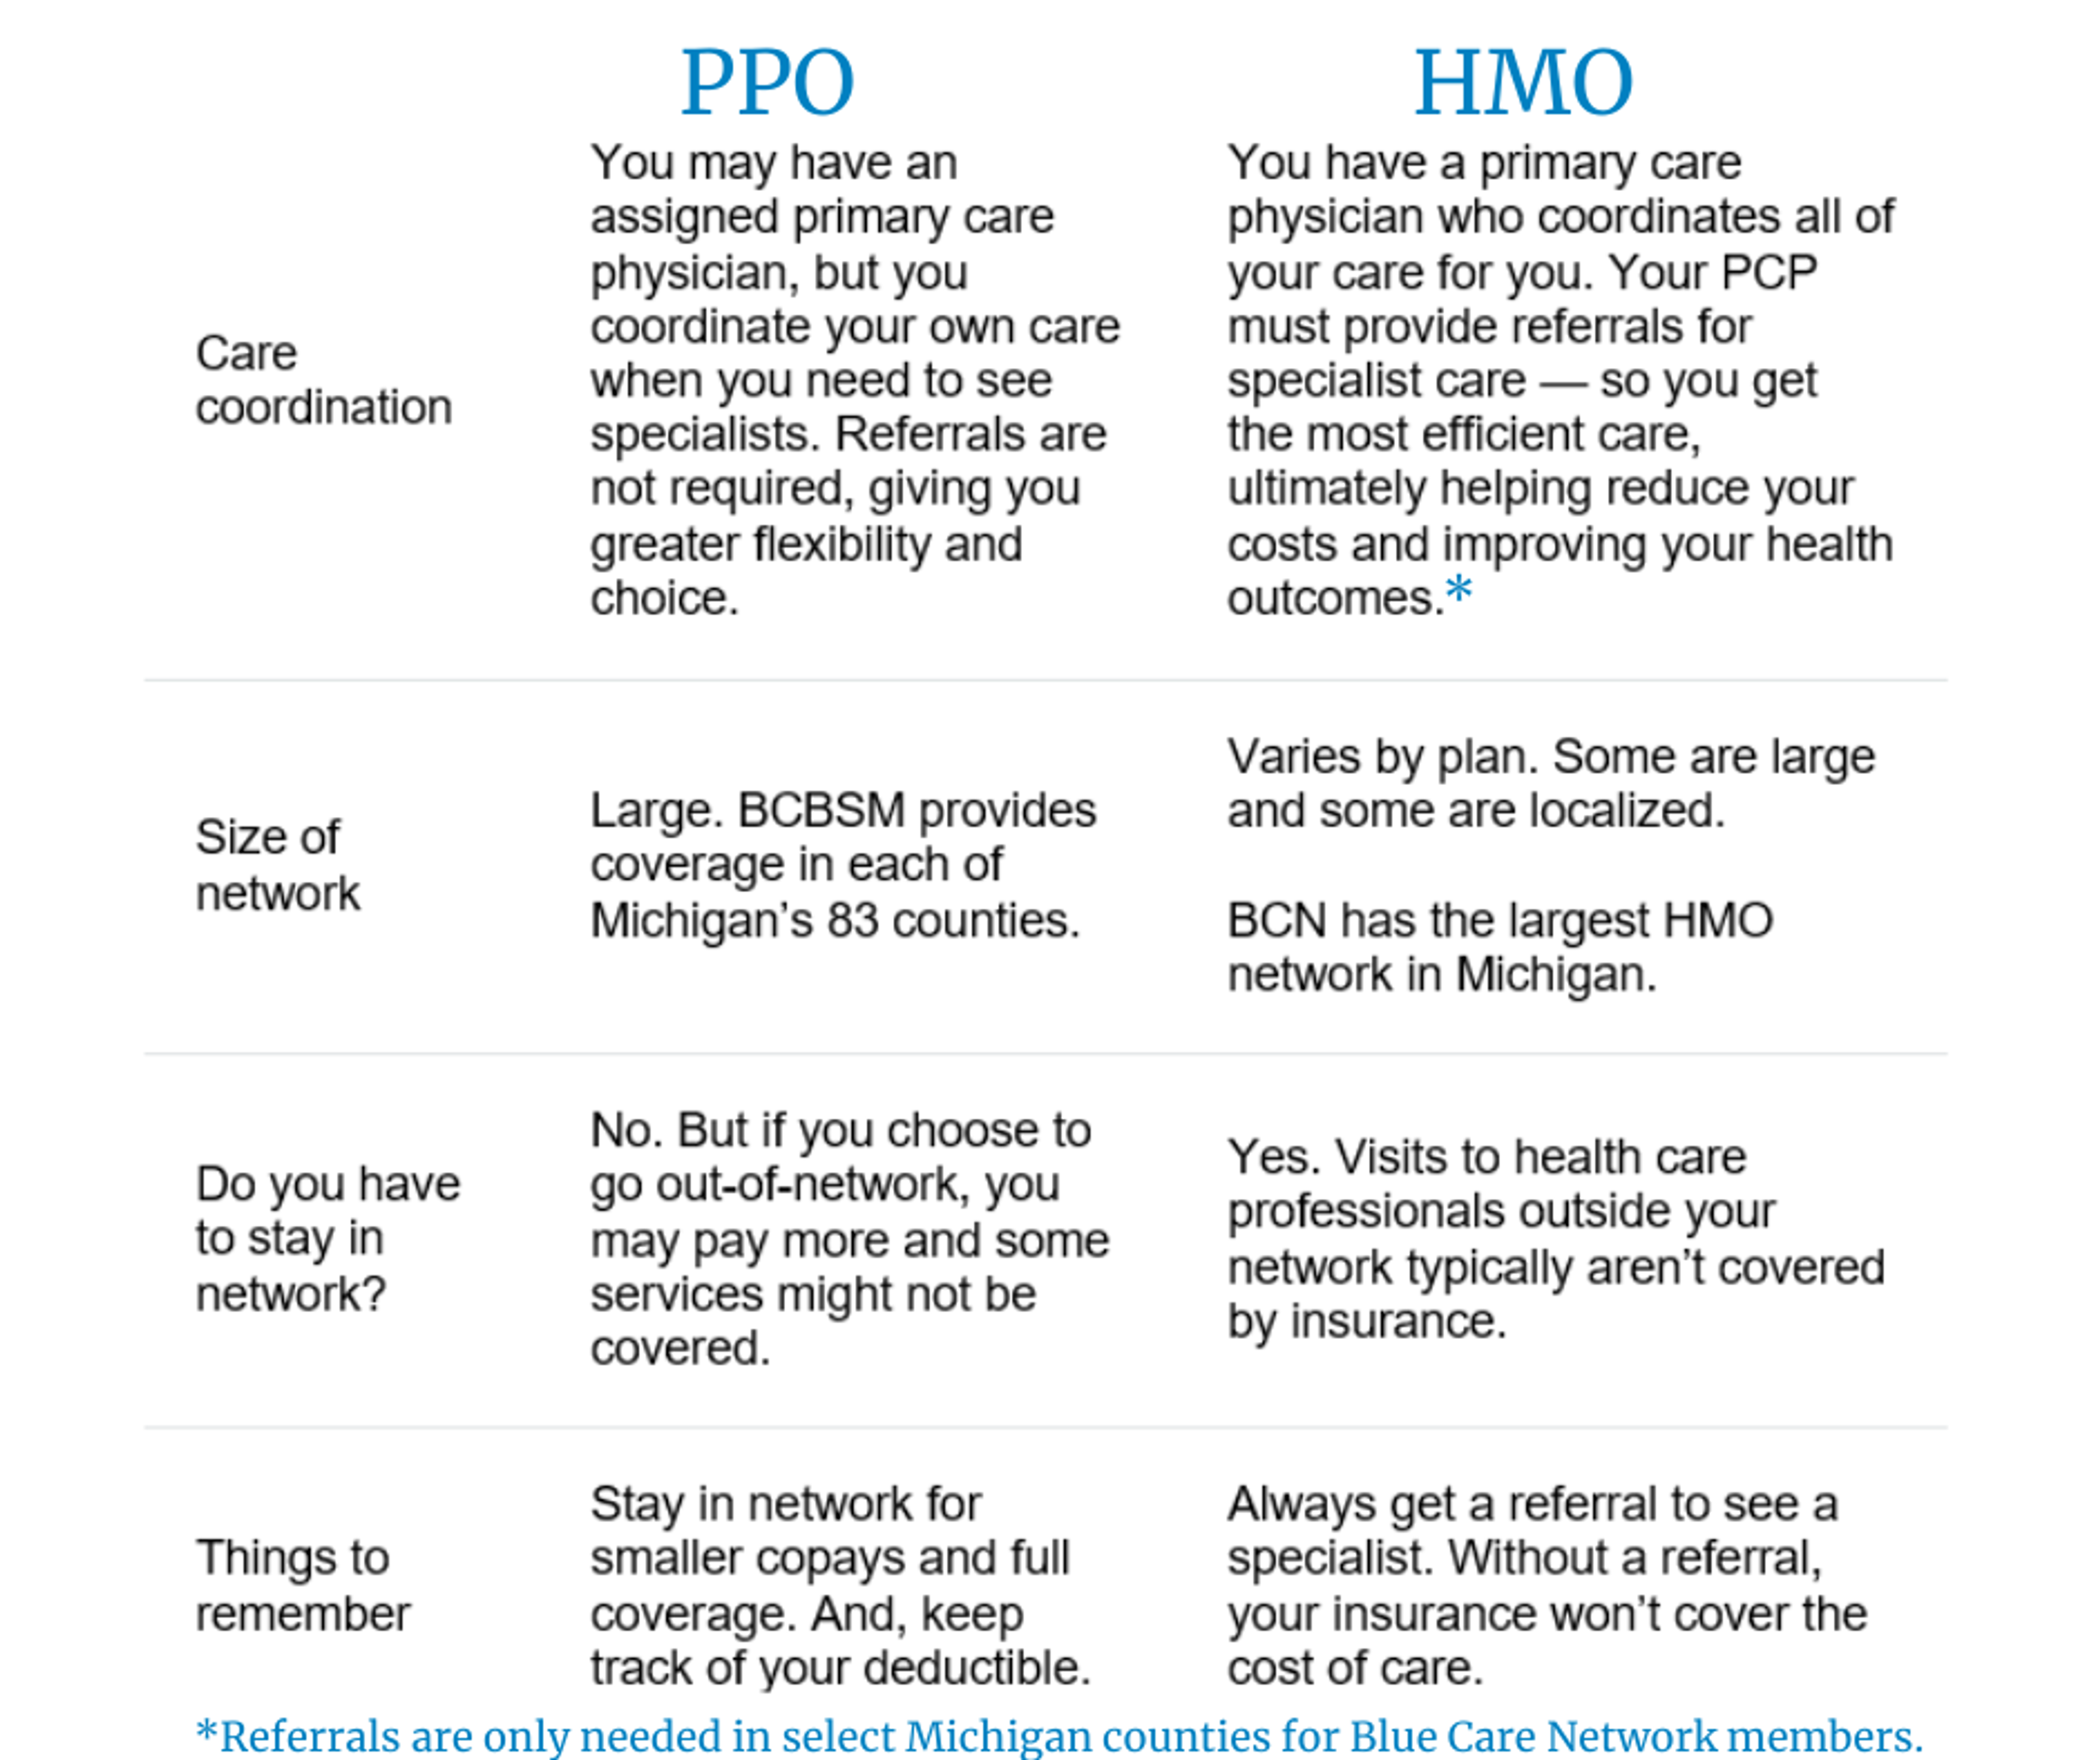
Nevertheless, understanding the distinctions in between particular health plans, like an HMO and a PPO plan, is necessary to protect the right health coverage for you, your household, or your employees. In this article, we'll stroll you through the key differences in between HMO and PPO strategies, evaluate their advantages and disadvantages, and reveal you how each strategy deals with a health repayment plan (HRA).
Since of this, these policies provide lower premiums and out-of-pocket costs. PPO strategies use more versatility in picking health companies and services than HMO plans. They frequently have higher premiums and deductibles, and require policyholders to submit their own claims for out-of-network care, which can be complicated and time-consuming.
An HMO is a kind of health strategy where a group of network medical professionals, health centers, and other treatment companies contract with an insurance coverage company to provide policyholders different covered services and items in exchange for a premium. Providers within the HMO network accept supply care to insurance policy holders at a decreased rate.
In 2023, 13% of workers in the U.S. with medical insurance coverage enrolled in an HMO plan1. Since these policies normally have lower premiums and out-of-pocket costs compared to other kinds of health plans, they can look like an attractive choice for those trying to find protection. The lower overall costs come with particular limitations.
Comparing PPO and HMO Health Coverage
Their HMO likewise will not cover the costs of out-of-network care or treatment from a professional that took place without a PCP recommendation, except if a policyholder requires emergency care. Before figuring out if an HMO matches you or your organization, you need to take a look at the advantages and disadvantages. HMO plans typically have low premiums and copayments.
Insurance in Irvine CAYour strategy will also generally cover in-network specialist care with only a little copay for services. When you register in an HMO strategy, you have to select a PCP who will be your primary point person to reach out to when you need care. In return, they collaborate your care, handle your general treatment, and make recommendations for professionals.
In addition, your PCP serves as your medical advocate, and you might establish a strong bond with them, resulting in you receiving better and more constant care. While these benefits of HMO plans might seem luring, there are possible disadvantages that you ought to consider before registering. If you desire your HMO to cover the cost of your care, you should get care from a specific network of providers in your area.
If you see a non-network supplier, you'll be accountable for your entire bill without the assistance of your insurer. If you need to go to a professional for treatment, you must ask your PCP for a referral for an in-network professional in advance. If your PCP does not refer you, you need to pay the whole expense of the expense alone, which can be expensive.
However, your policy will lay out the situations that it considers an emergency. If your emergency situation doesn't fit the requirements in your strategy, you'll need to foot the bill on your own. In 2023, the average yearly premium for a group HMO plan was $8,203 for self-only protection and $23,758 for household coverage2.
Insurance in Irvine CAReviewing Best Medicare Advantage Policies
For family protection, employers contributed $16,600, and staff members contributed $7,158. Like other kinds of health insurance, HMO policies might have an annual deductible. A deductible is the set amount of cash a plan participant need to pay out-of-pocket before their insurance provider starts to cover their medical care costs. In 2023, the typical deductible for an HMO plan was $1,200.
KFF found that 33% of people registered in a self-only HMO don't have a deductible3. (ACA) Market strategy was $9,100 for self-only coverage and $18,200 for household coverage4.
A PPO policy is a kind of health strategy in which an insurance service provider agreements with doctors, health care specialists, and medical centers to create a list of "preferred" health care service providers for insurance policy holders. When people with a PPO plan get treatment from an in-network supplier, their health insurance provider pays the supplier at an agreed-upon decreased rate.
PPOs are the most common plan that companies use. In 2023, 47% of people with a group health insurance strategy have a PPO2. These strategies are popular because they don't need members to select a PCP before registering and allow members to select from a bigger variety of in-network suppliers than they can with an HMO plan.
PPO strategies provide numerous advantages that make getting medical care a practical and favorable experience. PPO strategies have a large network of service providers providing the exact same types of medical services with set comparable prices.

Latest Posts
Final Expense and Burial Expense Planning

The Mechanics of Whole Life Coverage
Navigating Medicare Part D Coverage in 2026